A decade in finance, working with billion-dollar companies, and I couldn’t tell you if I was on track for retirement or my kids’ future without opening a dozen apps, a spreadsheet and my LLM of choice. That’s insane.
Nobody should need a finance degree to check their LLM, or £200,000 in assets to unlock an advisor just to know how they’re doing. With Haido, you just ask.
Part 1 of 6
$115 billion. $11 billion. $6 billion
I want to tell you how I got here because being adjacent to enormous wealth 3 times, and capturing very little of it, taught me hard lessons and motivated the heck out of me. It's why I'm building a generational AI wealth company.
Now, here's the part I don't usually admit. I've always run on a slightly delusional belief that the big win was coming, so the details would sort themselves out. The result: someone brilliant at the mission and absent minded about their own wealth.
$115 billion
I was employee 4 at Revolut and I left before my first vesting cliff. Yes — you read that correctly.
I had a difference of opinion with Nik about direction, so I left to found Flux. This summer Revolut hit $115bn. I think about that number more than I'd like to admit. I didn't stay and I was wrong. Very wrong. Revolut is the cornerstone of my antiportfolio. What Nik, Vlad and team built is a case study of its generation, and it changed how I build for the better. For that I'm grateful.
Lesson 1: Don't make a permanent decision on a temporary emotion. Lay your plans out clearly — especially the money ones — and consider scenario modelling for calm money decisions. Also, never underestimate Nik.
$11 billion
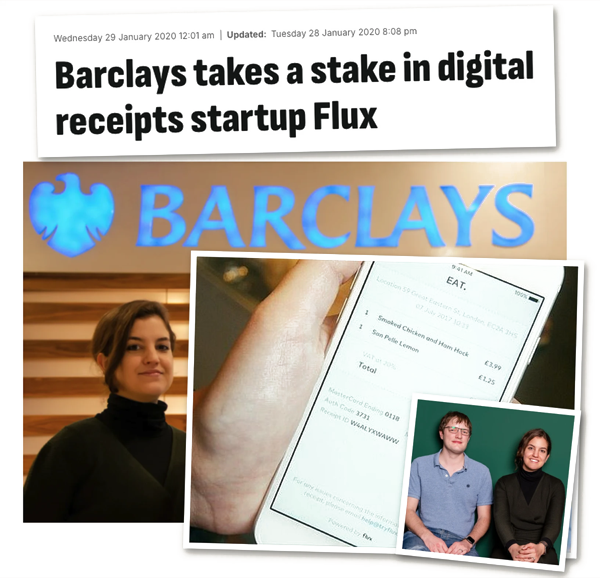
Flux launched in 2017 to build the infrastructure to digitise receipt data. We acquired 1.3m customers and built real-time integrations with giants like Barclays, Monzo, JustEat, H&M and more so that we could close the loop.
Flux itself wasn't worth $11 billion — but we very nearly joined a home that is today. We were flying, then post-COVID we weren't so we chose to sell and signed a good deal with a US startup. Then a large partner, uneasy about data moving, pulled out last minute. The sale collapsed. I said bye to what I thought was my life's work and welcomed our 1st baby the same month. Wild.
Lesson 2: Too many to write, DMs open for founder lessons. I would highlight that crocodile mode is real. Don't be ashamed to go still when you need to but keep waiting for the right moment. When it comes, take it with force.
$6 billion
After Flux I joined Monzo and saw the magic up close — the pre-IPO stage and a real learning curve after years in 0-to-1 mode. I'm a proud shareholder 🚀 .
But the quieter shift for me over the last decade is what mattered most.
Liquidating Flux broke my lack of focus on my own wealth. I got disciplined and intentional. No exit, no windfall - just focus and consistency. Today part of my portfolio quietly covers our household utilities. Tiny against this post — but I built it deliberately, and I'm proud of it.
Lesson 3: You can't improve what you don't measure. True across everything. Obvious out loud, forgotten constantly.
3 shots. 3 extraordinary learning curves & more financial wisdom than any windfall would have handed me.
Part 2 of 6
No one is coming to save you
77% of the UK working population isn't on course for a "moderate" retirement.
Moderate is £32,700 a year for a single person and £45,400 for a couple.
Even high earners aren't saved by their salaries. 61% of high-earner households are off track for a comfortable retirement.
Most of us aren't putting enough into pensions or investments like an ISA, and everyday life isn't making it easier. In the year to July 2026, regular pay rose 3.5%, while essentials like housing bills (4.6%) and fuel (15.5%) rose faster, and the UK's credit card borrowing grew 12.5%.
Candidly, I only recently cleared my credit cards and turned a corner on my own investment goals with my portfolio now paying utility bills like I mentioned in the last post. It took years. The hard news is there's no lottery ticket. This doesn't happen overnight.
The good news: financial health works a lot like physical health. With focus and the right tools, people and possibly coaches around you, small, consistent effort gets you there.
Here's what helped me turn that corner.
1. I stopped thinking small amounts didn't matter
Results compound, just like exercising every day. "I've only got pounds left after bills, so what's the point?" I hear this a lot when it comes to investing, and I used to feel the same way. But that's not a growth mindset; it's a defeatist one. So I set up a direct debit to a SIPP, Junior ISA and Investment ISA every month and never looked back.
2. I tied my spending to my goals
I got a clear view of what "good" looked like for our household spending. Ramit Sethi's Conscious Spending Plan worked for me because it balances enjoyment with discipline.
3. I learned about disciplined investing
I learn best from doers, not books. I watched Michael Taylor's UK-specific videos on investing and nerded out on Michael Alberse's nstagram where he shares how he built a passive income portfolio from nothing in the US.
4. I stopped treating tax as an afterthought
I spent real time digging into the complexity of being a US citizen and UK tax resident, invested in a great accountancy firm, and got my house in order. I stopped ignoring tax and started optimising for it.
If you're trying to figure out how you’re doing and make decisions in the 3 minute gap between kids and work, possibly hiding in the bathroom, I see you. Stay tuned for the waitlist.
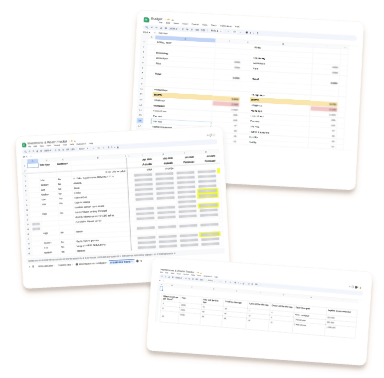
If you've got a 9-tab spreadsheet and a dozen accounts so you piece your money picture together by hand every time you need to make a decision, we're going to be best friends.
Part 3 of 6
How am I doing?
As of now, I’m feeling great. I’ve just hit 6 figures on my personal investment portfolio because of grit and focus. Part of it generates its own cash and pays all of my monthly utility bills, neat. I can also tell you how my pension pots are doing and where I expect to be in 30 years. I can tell you how much my kids will have ready for their first home deposit or university. I can tell you a lot about my money nearly instantly.
But that wasn’t the case just 4 years ago.
The reality is there comes an age where you really need to know how you’re doing when it comes to the big picture - the really important stuff like home ownership, retirement and possibly kids. This is not about budgeting my avocado toast. I’m looking for my kindred spirits here.
But where do we start? As mentioned you cannot improve what you don’t measure. But measuring is really hard and so time consuming because of the following.
We estimate that the average UK adult has over 10 unique financial accounts across separate institutions.
I’m talking your pension pots, savings accounts, credit cards, current accounts, mortgage, home equity, personal debt and more.
Just look at these stats for starters
- 2.4 pension pots scattered across old jobs — 2.9 if you're under 35 (Pensions Commission, May 2026)
- Savings spread across 2–4 different providers — true for almost half of UK savers (Statista, 2024)
- 2 or more current accounts on the go — true for 1 in 3 Brits, up 36% since 2015 (Zopa, via City AM)
Asking what should be a simple question, for example "how am I doing with my savings for that thing my family needs in 2 years" so that you can make different decisions that month when payroll lands requires either
- 5 hours a month manually updating spreadsheets
- Talking to Claude or ChatGPT which keeps forgetting and isn't updated
- Handing over control and 1–2% to an advisor (if you even meet their networth requirement)
What if it didn't need to be that way? 🤔
PS — I'm hiring. I'd love to hear from strong product engineers who aren't working closely enough with AI and feel like they're missing out. DMs are open.
Part 4 of 6
Now double it
So far in this series, we’ve reviewed that the average UK adult juggles 10 financial accounts and the fact that I welcomed my first child 4 years ago (I now have 2 for the record). That trigger moment made my husband and I realise we needed to fully merge our money so that we could start working as a team for the shared dreams we have for our new family.
With that in mind we doubled the accounts needed to sync up so we could plan and take action. That’s a lot of different platforms and mad complexity.
Somewhere in that blur of the newborn phase I decided that I would own it and that I needed to “mind my own business,” to borrow a line from Rich Dad Poor Dad.
As the self-appointed CFO (aka control freak) of the household, I was going to figure it out. Here’s what I did and the outcomes that followed.
📅 We started monthly family financial meetings, sometimes over WhatsApp. They're in the calendar and scheduled. We update all our numbers, review our goals, action anything off track and celebrate the focus
💸 I made sure we pay ourselves first, and that it mostly happens on autopilot. Salaries come in, money goes to Junior ISAs, our ISAs and savings accounts
🤝 Once we’ve "paid" ourselves, we each send a fixed amount to a joint account to cover shared expenses. Following that the rest of the money is to spend on life that month until the number hits zero on a debit card
🔢 I built a 9-tab interconnected spreadsheet keeping an eye on all of it. It has tabs for goals, summary, shared cashflow (what happened), budget (what we’re sticking to), pensions, investments, debts, and a few calculator tabs. The star is the summary page, bringing together our “why” and what's on/off track.
Outcome? Messy money became calm money. It nurtured psychological safety with money, networth growth and a portfolio that’s paying us a healthy amount of passive income.
Now, when it comes to money questions and getting on top of how you or we are doing, what's the solution?
I don't think it's
- A slightly better replica of this mammoth spreadsheet I have that takes me ages to update
- Another budgeting app with lower fees on savings or investments
- Definitely not a general untrained chatbot reviewing your statements and giving you outdated childcare hours earnings thresholds from 2022
I think it’s a radically different approach. This is only possible now because of new technology (not just AI...) and regulatory change.
All my experiences have come together to prepare me to build this product.
My professional life chapters so far have taught me
1️⃣ Morgan Stanley: Attention to detail and discipline
2️⃣ Revolut: Execution is everything and to use conviction with hyper speed to build product
3️⃣ Flux: Resilience, hustle and the power of ideas translated into action
4️⃣ Monzo: The true definition of customer obsession
I’m pulling that all together to bring you my next big thing. I can’t wait to show you 🫶
Part 5 of 6
“This is not financial advice” does not excuse slop
I’ve been quiet about exactly what I’m building. I haven’t been quiet about what brought me here. What I’m building has strong opinions about what the best product looks like and there are 2 beliefs I want to share before we hit the final post of this series.
1️⃣ “This is not financial advice” does not excuse incorrect answers, left unevaluated, with zero accountability surrounding one of the most important parts of a person’s life.
2️⃣ The knowledge and tools to build wealth and a positive net worth should not sit behind a £200k minimum.
Here’s why I feel so strongly.
28 million UK adults (56%) used AI to help manage their money in the past year (Lloyds Consumer Digital Index). Many of us are asking general-purpose chatbots to support us with our financial lives and a study of 18 AI models reported by the FT found they got personal finance questions wrong 57% of the time.
This is a problem.
Then just recently on the 19th of October, the FCA asked the providers of those models to add clearer and more consistent disclaimers because only 40% of consumers realise they have no recourse if they act on a wrong answer and it goes badly.
What does that tell me?
⭐ Consumer demand has officially outpaced the products that exist to best serve them ⭐
Confident answers, wrong more than half the time, about people’s pensions and their kids’ futures. Yet, people continue to use it because there is no alternative! Yet 🤗
Here’s what we're doing, and what I’d expect as standard:
✅ Accountability and traceability. AI is a fantastic conversational layer, never the excuse for a wrong answer. We’re accountable for every one. Every number is traceable to where it came from. Every answer is tested relentlessly against evaluations designed by qualified professionals with guardrails monitored for good customer outcomes. When it’s your life savings, “mostly right” isn’t a thing.
✅ A more inclusive business model. AI changes the economics and scale of what’s possible, so let’s use it.
My mission is to increase the wealth of every customer who uses our product, by democratising access to financial knowledge in a simple and responsible way. Nobody should need hours in a spreadsheet, a finance degree or £200,000 to know what’s going on with their money.
Part 6 of 6
Introducing Haido
It’s an acronym for “How am I doing?” and a nod to the core customer need. Everyone I speak to says the same thing: “I just want to know… how am I doing?”
Haido has one promise: know how you’re doing by talking to all of your money, via responsible AI.
I’m so proud to be back building with my co-founder Tom Reay and an elite senior team from Monzo, Deliveroo, Twitter, JustEat and Teller.